


Insurance Insights
Perspectives on protecting your home, business and everything you value.
How to Manage Multiple Insurance Policies Effectively
Quick Summary
Managing multiple insurance policies effectively starts with an inventory of every policy you hold, including carrier, limits, deductibles and renewal dates. Store everything in one organized system and review your coverage once a year to catch gaps, overlaps and missed renewals.
- List every policy with its carrier, coverage limits, deductibles, premium and renewal date.
- Store all policy documents in one digital folder and keep a master spreadsheet current.
- Build a comparison matrix to spot where two policies overlap or where no policy responds.
- Set calendar reminders 60 days before each renewal date so you have time to shop coverage.
- Review your full coverage once a year and after any major life or business change.
Table of Contents
- Why Managing Multiple Insurance Policies Gets Harder Over Time
- Step 1: Inventory Every Policy You Hold
- How to Organize Insurance Policies in One Place
- Finding Insurance Coverage Gaps and Overlaps
- Insurance Policy Review Checklist for Your Audit
- Using Digital Tools to Track Premiums and Renewals
- How Often to Review Insurance Coverage
- Scheduling Your First Coverage Review With Galt
- Frequently Asked Questions
Last Updated: November 4, 2026
How to manage multiple insurance policies effectively starts with one simple habit: knowing exactly what you own. Many homeowners, business owners, churches, restaurants and professionals carry several policies at once, and the same problems come up again and again.
Multiple policies are not a problem by themselves. The problem is managing them as separate files instead of one connected plan. A clear process keeps your coverage aligned with your life and business.
Why Managing Multiple Insurance Policies Gets Harder Over Time
Most people start with one policy, a home or auto plan. Over the years they add a renter’s or flood policy, a commercial plan, a umbrella policy, and maybe a professional liability policy. Each new policy often comes from a different carrier, with a different renewal date and a different claims phone number.
That spread creates three common problems:
- Missed renewals that lead to lapses or surprise premium jumps
- Overlapping coverage that you pay for twice
- Hidden gaps that appear only when something goes wrong
Each problem gets worse the longer you wait to deal with it. A quick annual review keeps the system manageable.
Step 1: Inventory Every Policy You Hold
Start by listing every policy you have. Do not rely on memory. Pull out your records and build a complete list.
For each policy, record:
- Carrier name and policy number
- Type of coverage (home, auto, commercial, liability, umbrella)
- Named insureds and covered properties or vehicles
Search your email, bank statements and filing cabinet for policy documents. Many people also find old policies they forgot to cancel. Mark any that you no longer need.
How to Organize Insurance Policies in One Place
Once you have your list, store everything in one central location. A single place makes it far easier to find information during a claim or a renewal.
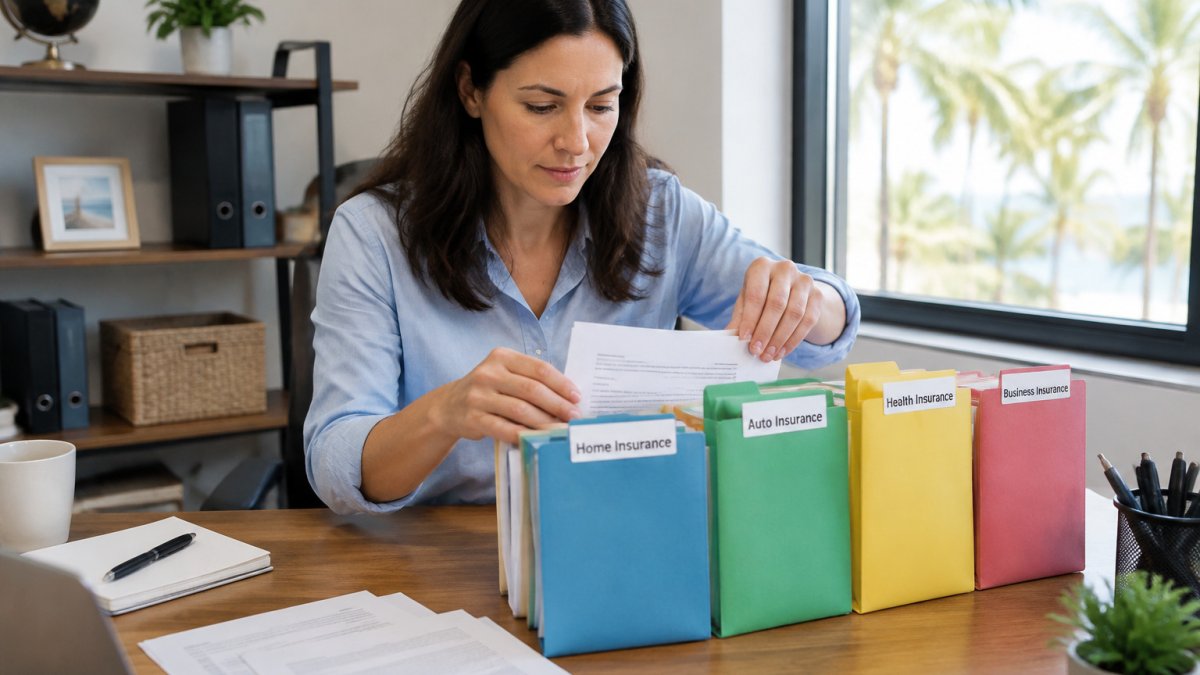
Here is a simple setup:
- One digital folder with a subfolder for each policy
- A master spreadsheet with the inventory details from Step 1
- A printed binder for policies you may need during a power outage or emergency
Name every file clearly, such as “2026 Auto Policy – State Farm.pdf.” Keep the master spreadsheet updated each time a policy changes.
Watch out: Storing documents only in one person’s email account can leave your family or business stuck during an emergency. Share access with a trusted person.
Galt Insurance builds this kind of consolidated view for clients, so one team can answer questions across every policy. coordinating multiple insurance policies shows how a professional handles this in practice.
Finding Insurance Coverage Gaps and Overlaps
Overlaps and gaps are the two biggest costs hiding in a multi-policy setup. Overlaps cost you extra premium. Gaps leave you exposed. To see how a unified program addresses both, read what a consolidated insurance program covers. The challenge is that both are invisible until you compare policies line by line.
A concrete comparison method
Instead of reading each policy in isolation, build a simple matrix. List your major asset and liability categories down the left side (home structure, personal property, auto, rental car, business property, business liability, professional services, umbrella). Across the top, list each policy. In each cell, note the coverage limit and deductible, or write “excluded.” This forces you to see where two policies overlap and where no policy responds.
Common patterns to look for:
- Home and auto liability stacking: An umbrella policy can sit above your home and auto liability limits and respond after those limits are exhausted. Without an umbrella, a serious at-fault accident can exceed both limits.
- Business property at home: A homeowners policy may cap business property (computers, inventory, tools) at a sublimit. A home-based business with significant equipment may have a gap unless a commercial policy or endorsement covers it.
- Flood and water damage: Standard homeowners policies commonly exclude flood, so a separate flood policy may be needed, and the definition of “flood” versus “water backup” matters at claim time (Buy a Flood Insurance Policy).
How coordination of benefits decides who pays
Coordination of benefits (COB) is the rule that decides which insurer pays first when more than one policy covers the same loss. The primary policy pays up to its limit, and the secondary policy can pay some or all of the remaining balance.
Knowing which policy is primary helps you avoid claim delays. It also tells you whether a second policy adds real value or just duplicates the first.
Tax implications of carrying multiple policies
Talk with your tax advisor about how each policy is classified, especially if you carry policies for both personal and business assets. Keep records that show which policy covers which activity, because commingling personal and business coverage can complicate both a claim and a deduction.
When to consolidate versus keep separate
Consolidation is not always the answer. Bundling home and auto with one carrier often earns a multi-policy discount, but it can also concentrate risk and reduce your leverage at renewal.
Watch out: Canceling an older policy before the new one is confirmed in writing can create a coverage gap.
The article describes three common coverage situations and what to look for in each, summarised below.
| Situation | What to check | Why it matters |
|---|---|---|
| Home and auto liability | Umbrella policy above liability limits | A serious accident can exceed both limits |
| Business property at home | Homeowners sublimit on business equipment | Home-based business equipment may be uncovered |
| Rental car | Auto policy and credit card coverage | Coverage may duplicate, costing extra |
| Flood and water damage | Standard policy exclusions | Standard homeowners policies commonly exclude flood |
Insurance Policy Review Checklist for Your Audit
Use this checklist to audit your coverage once a year:
- Every policy from your inventory is still active or intentionally cancelled
- Coverage limits still match the value of your home, vehicles and business assets
- Deductibles are affordable if a claim happens tomorrow
Marking each item as you go turns a long review into a focused task of about an hour.
Using Digital Tools to Track Premiums and Renewals
Most guides stop at “use a spreadsheet and set reminders.” That advice is fine, but it leaves the real work, automation, secure access, and a single source of truth, on your plate. A more effective approach uses a small stack of tools that each do one job well, so you spend minutes per month instead of hours per renewal.
Build a three-layer system
Think of your digital setup in three layers: capture, storage, and alerting.
- Capture layer: A master spreadsheet (Google Sheets, Microsoft Excel, or Apple Numbers) that holds one row per policy. Include columns for carrier, policy number, coverage type, limits, deductible, premium, payment frequency, renewal date, agent contact, and a link to the policy PDF. Use data validation for coverage type and a formula to calculate total monthly premium.
- Storage layer: A cloud folder (Google Drive, Dropbox, or OneDrive) with one subfolder per policy. Name files consistently, such as “2026-01 Auto – GEICO – Policy 123456.pdf.” Enable two-factor authentication on the account and share access with a trusted family member or business partner.
- Alerting layer: A calendar (Google Calendar, Outlook, or Apple Calendar) with recurring events for each renewal date, plus a second reminder 60 days ahead. For business policies, add a third reminder 90 days ahead so you have time to shop coverage.
Use automation to reduce manual checks
- Autopay with a confirmation habit: Set autopay with each carrier, then schedule a monthly 10-minute calendar event to scan your bank or credit card statement for each premium. This catches failed payments, duplicate charges, and rate changes before they become lapses.
- Email filters: Create a filter for each carrier’s domain (for example, “from:(@statefarm.com)”) that labels messages “Insurance” and skips the inbox. This keeps renewal notices and policy documents in one place without cluttering your day.
- Spreadsheet formulas: Add a column that calculates days until renewal using a formula like
=RenewalDate - TODAY(). Conditional formatting can turn the cell red when the renewal is within 60 days, giving you a visual dashboard without extra apps.
Consider insurance aggregator apps, with caution
Some apps and carrier portals let you view multiple policies in one dashboard. They can be convenient, but they often only show policies from participating carriers, and they may not include smaller or specialty insurers.
Watch out: Storing policy PDFs only in an email inbox or on a single laptop leaves you exposed to account lockouts, device failure, or a family emergency.
A monthly and annual rhythm
- Monthly (10 minutes): Confirm autopay cleared, update the spreadsheet if a premium changed, and check the renewal dashboard for any policy within 60 days.
- Annually (about an hour): Reconcile the spreadsheet against actual policy documents, update limits and deductibles, and archive expired policies in a separate folder.
This system is intentionally low-tech at its core, a spreadsheet and a calendar, with automation layered on top. It works whether you hold three policies or thirty, and it gives you a defensible record if a carrier disputes a payment or a coverage decision.
How Often to Review Insurance Coverage
Review your full coverage once a year, and again after any major life or business change. Common triggers include buying a home, adding a vehicle, hiring employees, opening a new location, or starting a new type of service.
Many people also review after a storm season or a major rate change, since these can alter your premiums and your exposure. A short review after each trigger keeps your plan current without a huge effort each time.
Scheduling Your First Coverage Review With Galt
If you hold several policies and are not sure they work together, a structured review is the fastest way to find out.
To get started, insurance policy reviews for Florida families explain what the process includes and how often families and businesses typically schedule one.
Galt Insurance provides tailored policies, manages your full insurance profile in one place, and gives you a dedicated team for a unified experience.
Frequently Asked Questions
How do you manage multiple insurance policies effectively?
Start by listing every policy in one document with the carrier, policy number, coverage limits, deductible, premium amount, and renewal date. Store digital copies in one shared folder and set calendar reminders 30 days before each renewal. Review the list at least once a year to confirm that each policy still matches your property, vehicles, staff, and business operations. Consolidating policies with one broker can also simplify billing and claims, but compare coverage terms before moving anything.
Is it better to have multiple insurance policies with one company?
Often it is, because one carrier can coordinate limits, avoid gaps between policies, and sometimes offer a multi-policy discount. The tradeoff is concentration: if that carrier denies or delays a claim, you have fewer alternatives. Ask for a side-by-side summary of coverage from each option, confirm how claims from one policy interact with another, and get the premium totals in writing before you decide. Pricing depends on your risk profile and location, so contact Galt Insurance for a quote.
How can you tell if multiple insurance policies overlap?
Compare the coverage sections of each policy line by line. Look for the same peril, such as water damage or liability for an employee’s driving, appearing in more than one policy. Overlap is not always wasteful, since some policies intentionally stack coverage, but it can mean you pay twice for the same protection. Also check exclusions and sublimits, because a gap often hides in a policy that appears to cover everything. A written review with your broker is the fastest way to confirm.
How often should you review your insurance policies?
Review all policies at least once a year and after any major change, such as buying a building, adding a vehicle, hiring staff, opening a new location, renovating, or changing how you use a property. Mid-term changes can leave a coverage gap that you won’t notice until you file a claim. Set the annual review on your calendar with the renewal dates so the work is done before premiums and terms are locked in.
