


Insurance Insights
Perspectives on protecting your home, business and everything you value.
What to Include in a Business Property Loss Report
Last Updated: October 29, 2026
Quick Summary
Every property loss report needs six core fields: incident date and time, cause of loss, location of loss, affected property itemized, repair or replacement costs with estimates attached, and supporting documents like photos and receipts. Build the report in the first 48 hours after a loss, since missing fields slow the claim.
- Split the report into three labeled sections: physical damage, extra expenses, and business interruption, each with its own running total.
- Cross-reference every claimed item and amount to specific evidence, such as a receipt number and photo number.
- Photograph serial and model numbers directly to settle ownership questions quickly.
- Do not estimate lost income from memory; use actual sales records and income statements instead.
- Add a higher second repair estimate rather than replacing the first, so the record shows how the number moved.
Table of Contents
- Essential Fields Every Property Loss Report Must Contain
- Building a Business Personal Property Inventory That Holds Up
- Your Commercial Property Loss Checklist for Evidence and Documentation
- Separating Physical Damage, Extra Expenses, and Business Interruption Loss Documentation
- How to Document Uncertain or Changing Repair Estimates
- Common Reporting Mistakes and How to Avoid Them
- Submitting Your Report and Preserving a Claim Trail with Galt Insurance
- Frequently Asked Questions
Essential Fields Every Property Loss Report Must Contain
A business property loss report records what was damaged, when, why, and what it will cost to fix. The report you build in the first 48 hours after a loss can strongly influence how smooth the claim goes. Miss a field and the claim adjuster will ask for it later, costing you time and money.
Every property loss report needs six core fields before anything else:
- Incident date and time of the loss
- Cause of loss, stated plainly
- Location of loss, down to the room or unit
Get these right and the rest of the claim moves faster.
Incident Date, Cause of Loss, and Location of Loss
Start with the basics, and be exact. Write the incident date and time the moment you discover damage, not when you think it started, if a pipe burst overnight, note when you found the water.
State the cause of loss in plain terms: water damage from a failed supply line, fire, storm, theft, or vandalism. Avoid guessing; write what you observed and let the adjuster confirm it.
For location of loss, name the building, then the specific area.
Affected Property and Business Personal Property Inventory
List every damaged item, separated into two buckets: the building itself and your business personal property. Business personal property covers the items you own and use to operate: furniture, fixtures, equipment, inventory, and supplies.
For each item, record four things:
- What it is
- How many
- Its age and condition before the loss
- What it cost to buy or replace
A common mistake is lumping “office equipment” into one line. Break it out, one damaged printer with a receipt is easy to value; “assorted equipment” is not.
Building a Business Personal Property Inventory That Holds Up
A strong business personal property inventory is the backbone of your claim. It proves what you owned and what it was worth. Build it before a loss if you can, and update it after.
Here is how we would structure it:
- Item description that a stranger could identify
- Quantity on hand
- Purchase date and original cost
Keep receipts, invoices, and sales records together, these supporting documents turn a list into evidence. Our property claims documentation guide shows how to record and organize this inventory so your claim stands on firmer ground.
One insider tip: photograph serial numbers directly. It settles ownership questions fast.
Your Commercial Property Loss Checklist for Evidence and Documentation
A commercial property loss checklist keeps you from missing evidence in the chaos after a loss. Work through it in order, and photograph as you go. Each line below corresponds to a field you should populate in your written loss report, not just a box to tick.
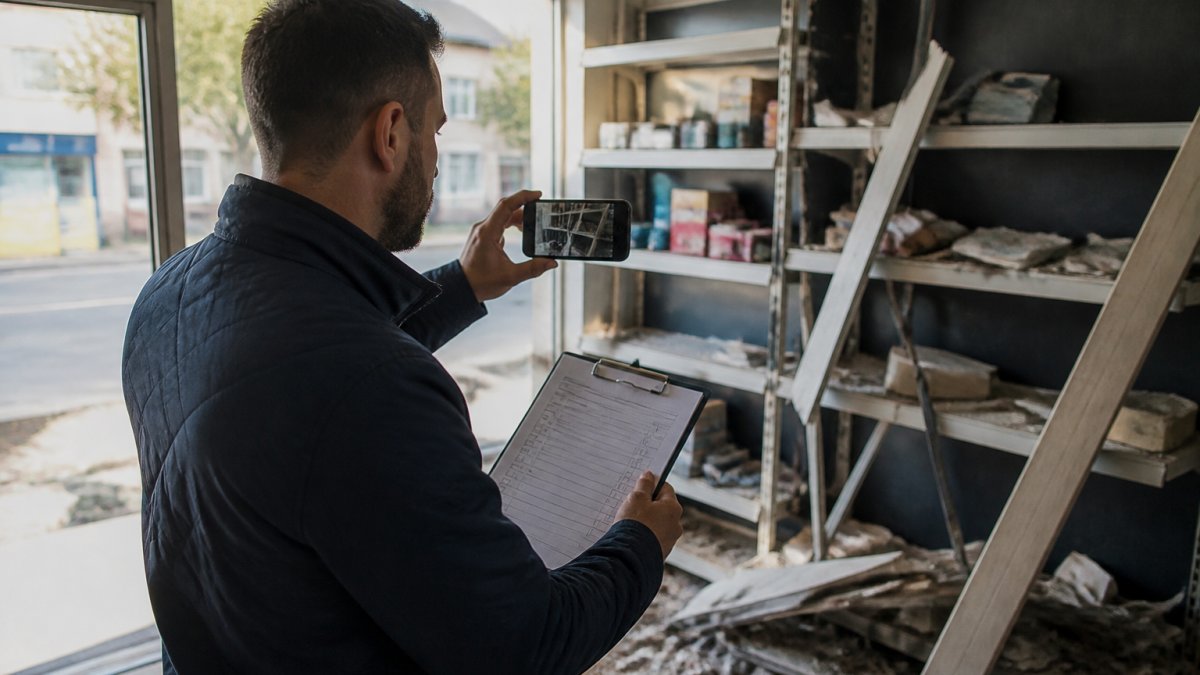
Comprehensive documentation of current damage serves as a vital baseline for future risk mitigation, much like how a consistent property maintenance checklist helps prevent the very vulnerabilities that lead to costly structural failures.
The Field-by-Field Report Structure
Use this as the skeleton of your report. The right-hand column shows what a completed entry looks like so you can see the level of specificity an adjuster expects.
| Report field | What to write | Sample completed entry |
|---|---|---|
| Incident date and time | Date, time, and how you discovered the loss | “10/14/2026, 7:15 a.m., discovered standing water in stockroom on opening” |
| Cause of loss | Plain-language observation, no guessing | “Water damage from failed supply line under breakroom sink” |
| Location of loss | Building, room, and area | “Main storefront, back stockroom, northeast corner” |
| Affected property | Itemized list, separated into building vs. business personal property | “Building: 400 sq ft drywall, baseboards. BPP: 2 shelving units, 1 printer, 14 cases of inventory” |
| Damage description | What happened to each item | “Shelving units: water-swollen particle board, non-salvageable. Printer: submerged power supply” |
| Repair or replacement cost | Written estimate or invoice attached | “Drywall repair estimate: $2,850 (attached). Printer replacement: $420 (receipt attached)” |
| Evidence reference | Photo numbers, receipt numbers, or file names | “Photos 001-014; receipt R-2214; estimate E-0912” |
| Business records | Income statement, sales records, or payroll showing normal operations | “Q3 2026 income statement attached; daily sales log 10/1-10/13 attached” |
Evidence Cross-References: The Step Most Reports Skip
The most useful habit you can build is cross-referencing every claimed item and amount to a specific piece of evidence. “Printer, $420” is weak; “printer, $420, receipt R-2214, photo 007” is a claim an adjuster can verify in seconds.
Build a simple evidence log alongside your report:
- Photo log: number every photo and note what it shows and where it was taken. “Photo 007: close-up of printer serial number, stockroom northeast corner.”
- Receipt log: list each receipt or invoice by number, date, vendor, and the item it supports.
- Estimate log: list each contractor estimate by number, date, scope, and the report line it supports.
Attach the logs when you submit. The adjuster can then match every dollar claimed to a document without calling you.
A Sample Completed Report Entry
Here is how a single damaged item should appear in the finished report, with all cross-references intact:
Item: HP LaserJet printer, model M404dn, serial [redacted]
Quantity: 1
Age and condition before loss: 3 years old, good working condition
Original cost: $420 (receipt R-2214, dated 09/2023)
Damage: Submerged power supply; unit will not power on
Estimated replacement cost: $420 (current vendor quote attached as E-0913)
Evidence: Photos 006-008 (wide shot of stockroom, close-up of unit, close-up of serial plate)
Report line: BPP-04
Repeat that structure for every item. It feels repetitive while you write it, but it is exactly what turns a list into a claim that pays.
The Checklist Itself
- Incident date, time, and how you discovered the loss
- Cause of loss in plain language
- Location of loss by building and area
Build the evidence log as you photograph, not afterward. Numbering photos on your phone as you take them takes seconds; reconstructing the sequence a week later takes hours and invites mistakes.
Photographs, Invoices, and Supporting Documents
Photographs are your strongest evidence. Take wide shots of the room, then close-ups of each damaged item, including a reference object for scale where it helps. Photograph serial and model numbers directly, it settles ownership questions fast.
Keep the originals. Invoices, purchase receipts, and sales records back up your values. For a full walkthrough, see our guide on how to document property damage for a claim.
Separating Physical Damage, Extra Expenses, and Business Interruption Loss Documentation
Business interruption loss documentation covers the income you lost while your business could not operate normally. Keep it separate from physical damage and extra expenses. Blending the three is one of the most common reporting mistakes we see, and the one most likely to slow a claim, because each category is governed by a different part of your policy and supported by a different set of records.
Split your report into three clear parts, each with its own section, evidence log, and running total:
Part 1: Physical Damage
This is the tangible loss, the building, equipment, furniture, fixtures, and inventory harmed by the event. Document it with the field-by-field structure and evidence cross-references described above. The key discipline is itemization: one line per item, one evidence reference per line, and a clear separation between building property and business personal property.
Part 2: Extra Expenses
Extra expenses are the costs you incur to keep operating or to mitigate further damage, temporary space, emergency repairs, rental equipment, overtime labor, or expedited shipping. These are not the same as the cost to repair the damage itself, and they are often recoverable under a separate coverage grant or sublimit.
Document each extra expense with:
- What the expense was and why it was necessary (e.g., “temporary storage unit to house undamaged inventory while stockroom is dried out”)
- The date incurred and the period covered
- The invoice or receipt, logged by number
A common pattern is lumping emergency repairs into the physical damage total. Keep them separate, emergency mitigation costs and permanent repair costs are often evaluated against different policy provisions and deductibles.
Part 3: Business Interruption
Business interruption covers the income you lost and the continuing expenses you incurred while operations were suspended. Support it with records that show what normal looked like before the loss:
- Income statements for the months before the loss, and for the same months in the prior year if your business is seasonal
- Sales records, daily or weekly sales logs, point-of-sale reports, or booking records
- Payroll records showing continuing labor costs
The timeline matters more than most people realize. A clear, dated timeline helps show when the loss began affecting revenue and when normal operations returned.
Do not estimate lost income from memory. Use your actual sales records and income statements. An unsupported interruption figure is the fastest way to have that portion of the claim reduced or denied.
Keeping the Three Categories Clean
Use a single report with three clearly labeled sections, each with its own running total. Do not net extra expenses against physical damage, and do not fold lost income into either. If a single invoice covers both a repair and an extra expense, say, an emergency plumber who both stops the leak and replaces a fixture, split it into components and reference each in the correct section.
If business interruption coverage is part of your policy, our business interruption insurance overview explains how the coverage works and what documentation it expects.
How to Document Uncertain or Changing Repair Estimates
Repair estimates change. Contractors find hidden damage, and materials get repriced. Document what you know now and flag what is still open.
Write each estimate with three parts:
- The scope of work described
- The labor and materials broken out
- A clear note that the figure is preliminary
Attach the contractor’s written estimate as a supporting document. If a second estimate comes in higher, add it rather than replacing the first, a loss record that shows how the number moved is stronger than one clean final figure with no history.
Watch out: submitting a single rough verbal estimate as final can undercut your claim before the adjuster ever inspects the property.
Common Reporting Mistakes and How to Avoid Them
Most weak claims fail on documentation, not on coverage. Avoid these mistakes and your report will do its job.
- Estimating instead of documenting. Use receipts and written estimates, not memory.
- Mixing locations. One report per site keeps the record clean.
- Skipping the cause of loss. State what you observed, plainly.
The real difference between a fast claim and a slow one comes down to how completely you documented the loss record from day one.
Submitting Your Report and Preserving a Claim Trail with Galt Insurance
Send your report to your insurer and keep proof you sent it. Save dated copies, note who received it, and log every follow-up, that trail protects you if questions arise later.
Working with a dedicated team can help. You can find more information on our claims page, and our guide on how to file a commercial property claim walks through what happens after you submit.
Frequently Asked Questions
What information should a business property loss report include?
A complete property loss report should include the incident date, cause of loss, location of loss, a detailed business personal property inventory, photographs and invoices, repair estimates, and separate sections for extra expenses and business interruption. Include your policy number, deductible, and contact information for your claim adjuster. Attach supporting documents such as sales records, tax records, and expense receipts to substantiate your claim.
How do I document business property damage for an insurance claim?
Start by photographing and videoing all damaged property before moving anything. Create a business personal property inventory listing each item, its age, original cost, and replacement cost. Gather purchase invoices, repair estimates from licensed contractors, and any available formal appraisal. Keep damaged items available for inspection unless they pose a safety risk. Use a commercial property loss checklist to ensure you capture building, equipment, furniture, fixtures, and inventory losses separately.
Should a business property loss report include lost income?
Yes, if your policy includes business interruption coverage. Document lost income separately from physical damage using income statements, sales records, and operating expenses. Show the projected income you would have earned during the recovery period and the extra expenses incurred to keep operating. This business interruption loss documentation helps your claim adjuster calculate your business income loss accurately.
What should I do with damaged property before an insurance inspection?
Do not discard damaged property until your claim adjuster has inspected it, unless it creates a health or safety hazard. Move undamaged items away from the affected area and photograph everything in place first. If you must dispose of perishable or hazardous items, document them thoroughly with photos and keep a log of what was discarded and why. This protects your claim and supports the values in your business personal property inventory.
A loss never arrives at a good time. The businesses that recover fastest are the ones whose documentation was ready before the damage happened. Galt Insurance builds tailored policies around your buildings, equipment, and inventory, keeps your whole profile in one place, and gives you a dedicated team that advocates for you when you file. Get started with Galt Insurance and give your business a faster path back to normal.
